Revenue recognition software applies an approved accounting treatment to contracts, produces revenue schedules and supports the related ledger entries. It can reduce recurring calculations and reconciliation work while preserving the evidence behind the result.
The software still needs the right inputs and policy. A billing date, payment date and revenue recognition date can differ, so evaluate those events separately.
What accounting decisions come before the schedule?
Finance needs to establish the contract, its performance obligations, the transaction price, the allocation and when the business satisfies those obligations. The IFRS Foundation's IFRS 15 overview describes this framework.
The resulting policy determines what the software should calculate. A system can apply a release pattern consistently while applying an inappropriate pattern to the contract. Keep the reasoning and approval connected to the schedule.
For a SaaS business, the SaaS revenue recognition guide illustrates the questions raised by subscriptions, setup work and amendments.
Which contracts should you test?
Use a representative set rather than only the standard annual subscription. Include a non-standard service period, an upgrade, a cancellation and a contract with several components where those occur in your business.
Ask the vendor to show how the original terms become a schedule, how a reviewer approves the treatment and what happens after a change. Inspect any proposed adjustment before it reaches the ledger.
Retain the original agreement and subsequent amendments. The reviewer needs to see why the current schedule differs from the one originally approved.
How do you test a cancellation and credit note?
Start with an illustrative €12,000 subscription for twelve equal monthly service periods. Assume one service obligation, even delivery, no tax or variable charges, and finance approval of €1,000 revenue per month. The customer pays the full invoice at the start.
At the end of month six, suppose both parties agree to cancel only the six undelivered months and refund €6,000. Under those assumptions, use these amounts to check the demonstration:
| Measure | Before cancellation | After the credit and refund |
|---|---|---|
| Recognised revenue for services delivered | €6,000 | €6,000 |
| Amount billed, net of credits | €12,000 | €6,000 |
| Cash received, net of refund | €12,000 | €6,000 |
| Amount remaining for future recognition | €6,000 | €0 |
Trace the contract amendment, credit note, refund and remaining schedule separately. A credit note reducing the customer's balance does not by itself prove that future releases stopped. Ask the reviewer to reconcile the resulting ledger balances and check for revenue that would otherwise continue after cancellation.
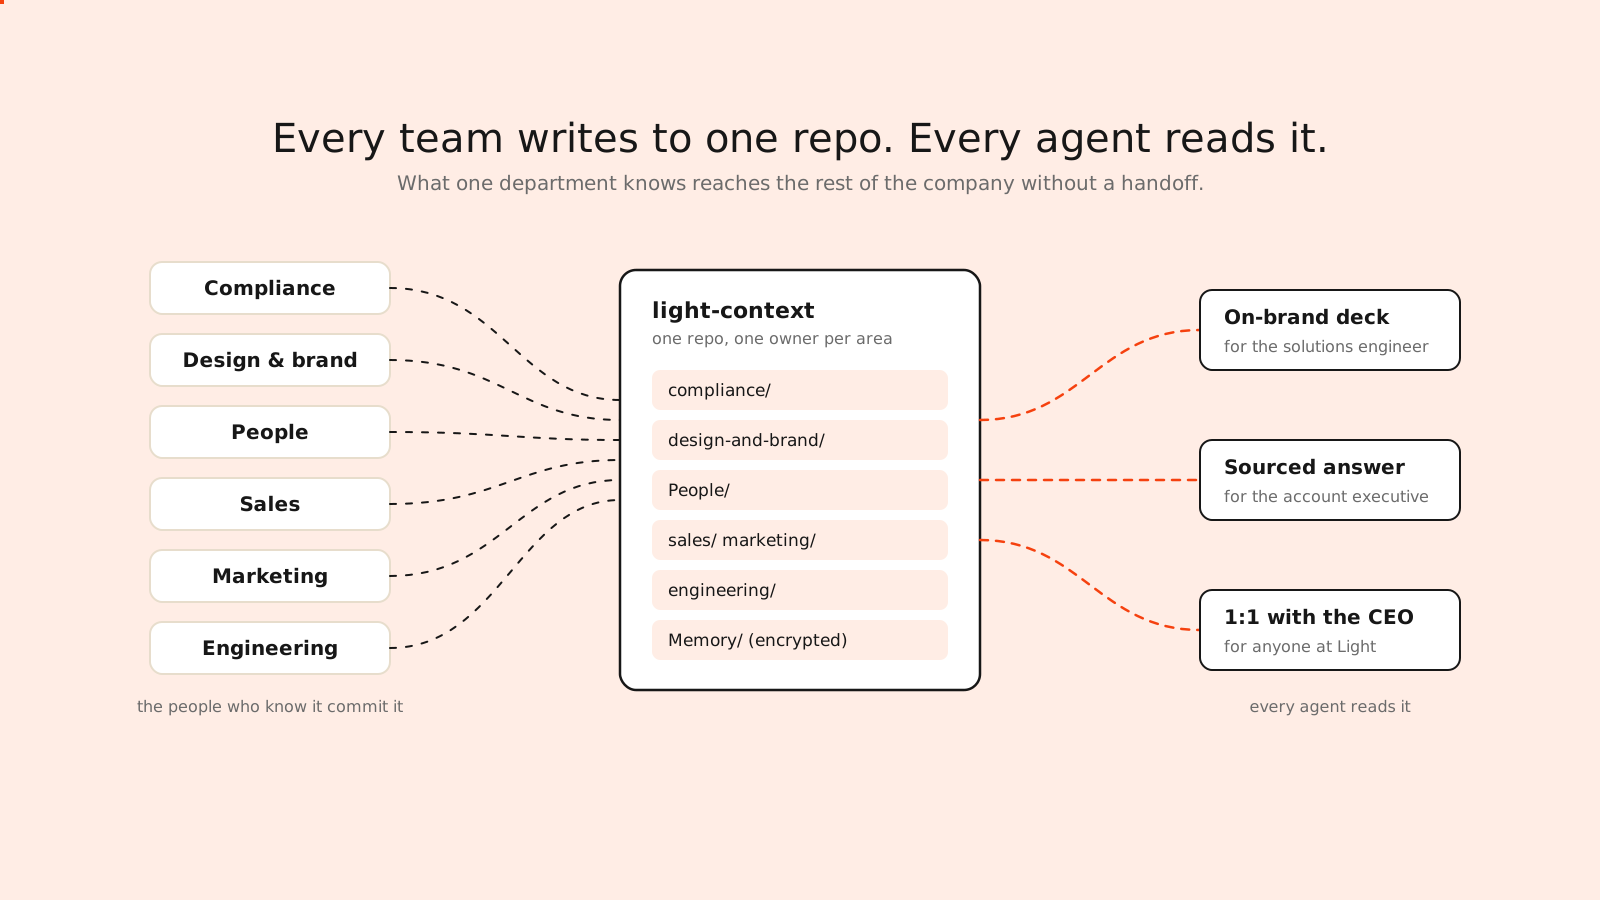
Different contract terms can change the treatment. Finance must establish the appropriate conclusion before testing the system. For Light, use the contract lifecycle documentation and the subscription management overview to frame the demonstration, including manual adjustments and exception ownership.
How should finance reconcile the output?
Start with the opening balances, follow the relevant activity and adjustments, and agree the closing position to the ledger. The detail should let finance explain a contract's contribution to a reported balance.
Then test a late correction. Can the system distinguish an open-period change from an adjustment that affects a period already closed? Can another reviewer reproduce the schedule that supported the previous report?
The financial close software guide covers the surrounding period controls and review evidence.
Does one system make ARR and revenue equal?
No. ARR is a recurring revenue run-rate measure defined by the business. Recognised revenue follows the applicable accounting treatment for the reporting period. Invoiced amounts and cash are different measures again.
A connected system can help finance explain the bridge between them by retaining consistent contract and transaction references. The differences still have meaning. A report that forces the figures to agree can conceal a definition or timing problem.
The management reporting guide explains how to document those metrics for a board pack.
What does Light provide?
Light's subscription management product describes contract-based billing and revenue recognition templates for IFRS 15 and ASC 606 workflows. Evaluate the supported treatment against your contracts and finance team's approved policy.
Ask to see a normal schedule, an amendment and the resulting ledger reconciliation. Confirm any product gap directly instead of assuming that an accounting-standard label covers every arrangement.
What should improve after implementation?
Measure preparation time, manual schedule changes, unexplained differences and post-close corrections. Include the time people spend maintaining inputs and reviewing exceptions.
The objective is a revenue number the team can trace back to the contract and explain under its policy. Faster schedule generation is valuable when it supports that result.
Explore how revenue recognition fits into accounting software for SaaS companies and accounting software for marketplaces.