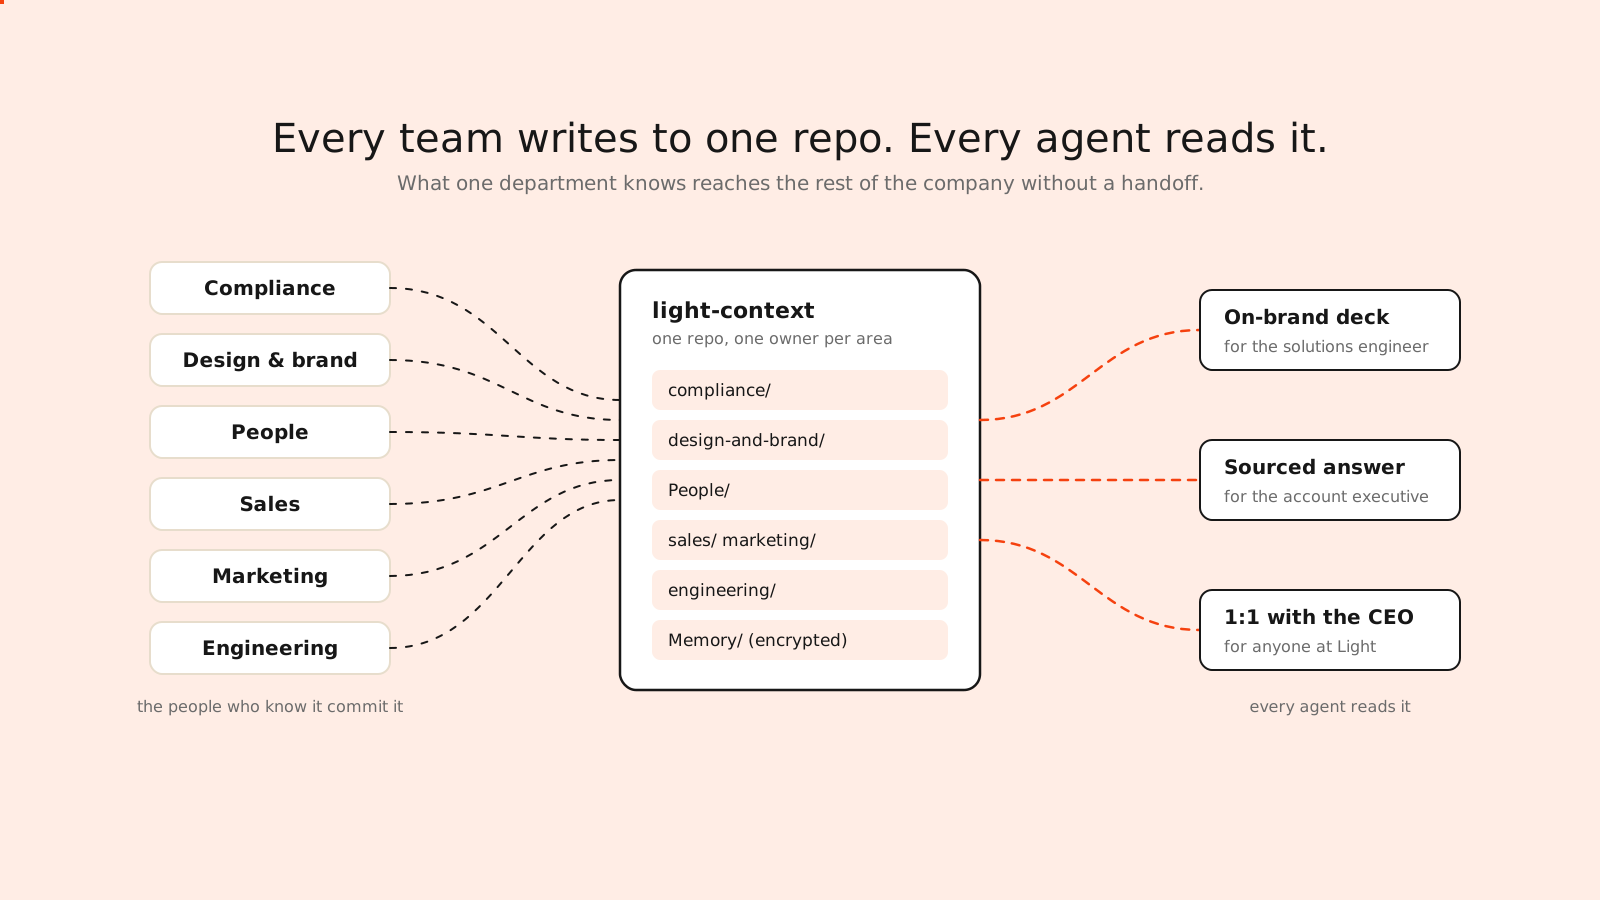
Financial consolidation software combines the accounting results of a parent and its subsidiaries into group financial statements. It supports the mappings, adjustments, currency translation and eliminations needed to present the group as a whole.
A shared accounting platform can reduce the work of collecting and reconciling data. It does not remove the accounting decisions behind consolidation or the need to retain each legal entity's records.
What should the consolidation process cover?
Start with the group structure and reporting basis. Confirm which entities enter the consolidation, the relevant ownership information and the periods the group reports on.
Then inspect the path from local accounts to the group result. The team needs controlled mappings, consistent accounting policies where required, foreign currency translation and appropriate consolidation adjustments. Intercompany balances and transactions need identification and elimination under the applicable treatment.
For the governing principles, consult the IFRS Foundation's IFRS 10 overview. The software must support the accounting conclusions the group adopts; it cannot establish the consolidation scope from an organisation chart alone.
How should the team organise consolidation each period?
Agree a reporting timetable and name an owner and reviewer for each entity's submission. Record the reporting period, currency, accounting basis and mapping version alongside the data so the group team can identify what it has received and what is still missing.
A practical review sequence is:
- Check each entity's submitted balances against its underlying records and resolve incomplete or inconsistent inputs.
- Review changes to account mappings and document how local accounts feed the group reporting structure.
- Track intercompany differences and other exceptions with an owner, supporting evidence and a resolution status.
- Retain the source and review history for consolidation adjustments, including changes made after the first report.
- Review the group result and record who approved it, together with any outstanding questions.
Keep this process workable for a late submission or a newly acquired entity. Software evaluation should include those cases, rather than assume every entity supplies clean data on time. The financial reporting guide covers tracing figures back to their source and reproducing a reviewed report.
Should you consolidate separate ledgers or use one platform?
Both approaches can work. A separate consolidation layer can be useful when entities must retain local systems or when an acquisition creates a transitional setup. It needs reliable data transfers and controlled mappings.
A shared finance platform can reduce repeated extraction and mapping by keeping more of the records together. It still needs entity boundaries, permissions and a way to handle local and group reporting differences.
Compare the full operating process, including who resolves discrepancies and maintains mappings. The multi-entity accounting guide helps evaluate the underlying ledger decision.
Which cases should you demonstrate?
Use the group's own structure and include a few deliberately difficult cases:
- Two entities record an intercompany item in different periods.
- A subsidiary uses a different functional currency from the group's presentation currency.
- A late adjustment arrives after the first consolidated report.
- The group adds an entity with a different chart of accounts.
Ask the vendor to show the adjustment history and the trace from the consolidated figure to its source. Inspect how changes affect reports the team has already reviewed.
Start with the worked €10,000 intercompany elimination example. It follows a service charge through both entities' books and the group adjustments, giving the team a known result to check before adding difficult cases. The multi-currency guide separates remeasurement from group translation.
How does Light support consolidation?
Light's financial consolidation software connects entity records, intercompany eliminations, currency handling and group reporting within the finance platform. That makes it relevant when a group wants to reduce recurring data handoffs as well as produce the consolidated result.
Bring the actual entity structure and reporting requirements to the evaluation. Ask the team to demonstrate the ownership arrangements, accounting treatments and review process that apply to your group. A straightforward wholly owned structure and a complex acquisition require different evidence.
What can a customer example tell you?
Paebbl's customer story describes a group using three ERP general ledgers, with manual intercompany invoicing and no shared view of spending and cash flow. VP Finance Christoph Zinsser explains how moving to Light gave the team a group view and changed the work behind it.
Use that story to make the evaluation specific: which systems feed your group report, which intercompany steps need manual work, and how will finance trace a consolidated number to its source? Paebbl's experience provides evidence of one customer's setup. Ask for a demonstration of your own structure before assuming the same result.
How do entity currencies and eliminations change group revenue?
Consider two wholly owned entities in one reporting period, with euros as the group presentation currency. This simplified example shows the revenue line only. It excludes taxes, other consolidation adjustments and the balance-sheet translation reserve.
Assume the euro entity reports €100,000 revenue, including a €10,000 service charge to the UK entity. The UK entity reports £40,000 external revenue and has consumed and recorded the internal service. For this example, assume €1.20 per pound is the appropriate translation rate for all the UK revenue in the period.
| Step | Calculation | Group revenue |
|---|---|---|
| Euro entity | Revenue in the group currency | €100,000 |
| UK entity | £40,000 × €1.20 | €48,000 |
| Combined revenue | €100,000 + €48,000 | €148,000 |
| Internal revenue elimination | Remove the €10,000 service charge | (€10,000) |
| Consolidated external revenue | €148,000 less €10,000 | €138,000 |
The group also eliminates the matching internal expense. Both entities keep their local records. The result contains €138,000 of external revenue; it does not establish group profit, cash or the full balance sheet.
For a real group, finance selects rates and accounting treatments under the applicable framework. IAS 21 addresses translation, and the intercompany example shows both sides of the service-charge entries. In Light, test the entity, subtotal, elimination and consolidated columns using the reporting guide.
How should you measure improvement?
Track the time spent collecting data, resolving differences, preparing adjustments and reviewing the result separately. A faster report generation step may leave the biggest bottleneck untouched.
Also measure whether another person can reproduce the consolidation and explain its adjustments. The aim is a group result the team can deliver and defend consistently, with less dependence on private spreadsheets and individual memory.
For group structures built around physical sites and projects, explore accounting software for clinics and accounting software for energy businesses.